
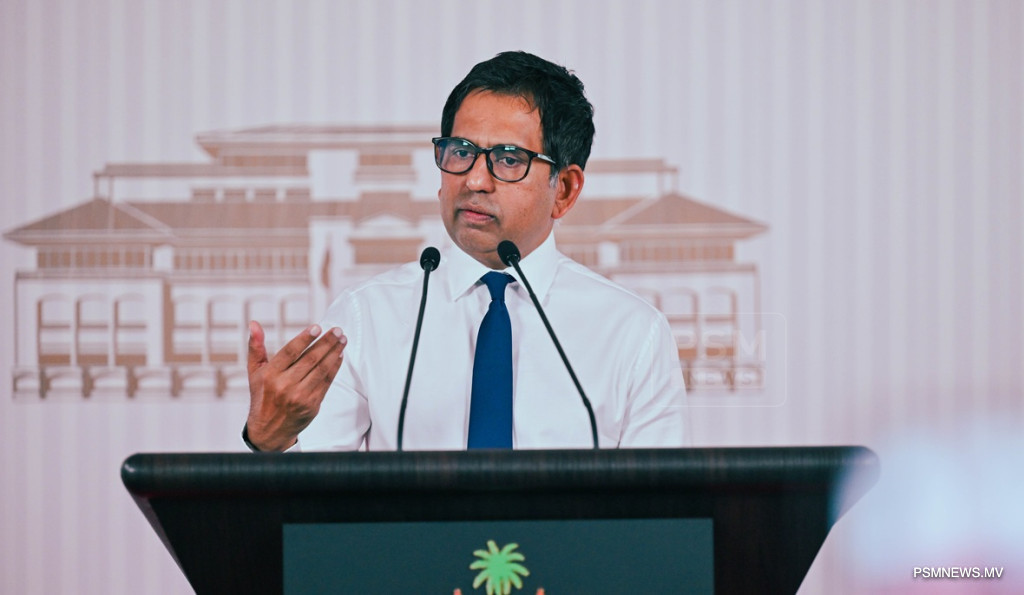
The Maldives is implementing updated foreign investment requirements to strengthen local participation in key economic sectors, with 29 foreign investments in sectors reserved for Maldivians having been discontinued so far, Minister of Economic Development, Transport and Trade Mohamed Saeed has said.
Speaking at a press conference at the President’s Office, Minister Saeed said 150 foreign investments are required to meet the new conditions introduced under the policy developed in line with the Foreign Investment Act, which came into effect in 2024. Seventeen foreign investors have already submitted applications to comply with the revised requirements.
The updated policy aims to create greater opportunities for Maldivian businesses while maintaining avenues for foreign investment in sectors where international expertise and experience can contribute to economic development.
The sectors covered by the revised requirements include wholesale and retail trade, logistics, and general sales, passenger sales and cargo sales agencies representing airlines operating in the Maldives.
Minister Saeed said 17 businesses previously operating in wholesale and retail trade had expressed interest in bringing Maldivian shareholders into their operations, with the ministry working to facilitate a structured process for compliance.
He said the process requires appropriate legal and professional procedures, including the formalisation and notarisation of partnership documents, to ensure that local participation is meaningful and properly established.
The government is working with relevant professionals to identify practical arrangements for implementing the new requirements, the minister added.
The Economic Ministry said the policy is designed to give Maldivians greater opportunities in sectors where local businesses have the potential to grow, while retaining foreign investment opportunities in areas where international expertise is valuable.
To support an orderly transition, existing foreign investors operating in newly reserved sectors will be given time to restructure their businesses or transition out of those activities. The ministry has also indicated that joint ventures and partnerships with Maldivian shareholders will remain possible in certain sectors, providing a framework for continued cooperation between local and international businesses.
Under the revised requirements, additional sectors have been reserved for Maldivians or made subject to local ownership conditions. These include wholesale and retail trade, logistics, general maritime transport services, banking services, construction projects valued below USD 15 million, real estate projects valued below USD 100 million, auditing and information technology services.
Foreign investors may participate in construction projects valued below USD 15 million, real estate projects valued below USD 100 million, and auditing and information technology services, provided Maldivians hold at least a 25 per cent share.
Residential real estate projects valued below USD 100 million and general sea transport services have also been reserved for Maldivians.
The ministry said the revised framework seeks to strengthen domestic entrepreneurship and ensure that more economic opportunities are accessible to Maldivians, while providing scope for foreign investors to contribute through permitted investment structures and partnerships.