
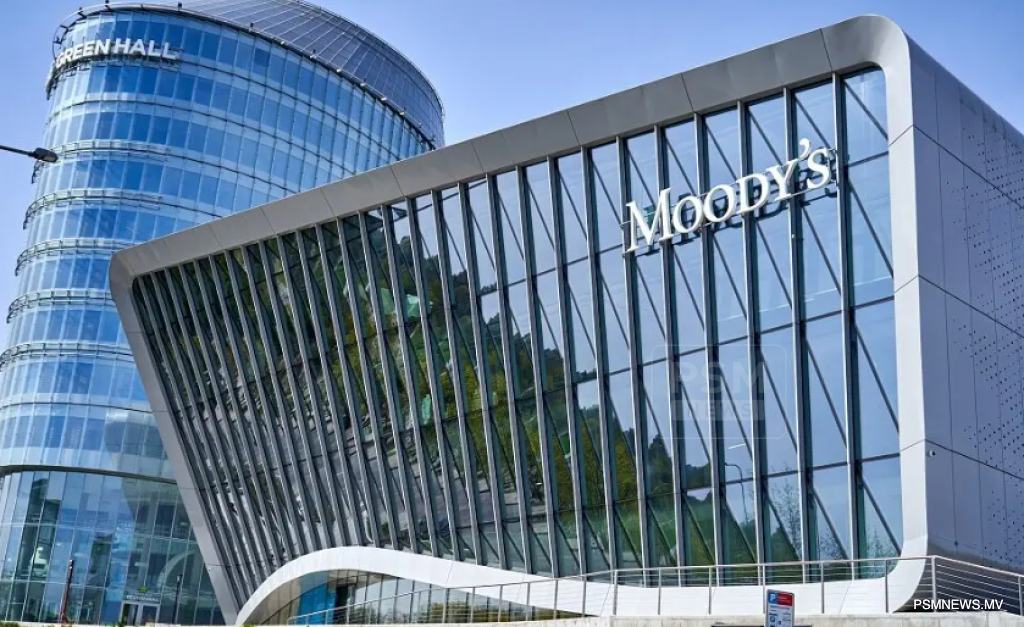
International credit rating agency Moody’s has upgraded the Maldives’ credit rating from Caa2 to Caa1, with a stable outlook, citing the effectiveness of the Government’s measures to strengthen fiscal stability.
Moody’s said the upgrade reflects the positive results emerging from the Government’s policies, progress made in debt repayment and measures taken to strengthen financial stability, which have significantly reduced the risks associated with the Maldives’ ability to meet its debt obligations over the near term.
According to a statement issued by the Ministry of Finance and Public Enterprises, key factors behind the upgrade include the repayment and settlement of a USD 500 million sukuk in April this year, the settlement of a USD 400 million currency swap facility, and the repayment of a total of USD 100 million in Treasury Bills in May and September.
The Ministry also highlighted the extension of the maturity of a USD 100 million Eurobond to 2031, saying the measure has reduced near-term debt repayment pressures.
The Finance Ministry said Moody’s also recognised the strengthening of the Maldives’ foreign exchange reserves, the increased funds accumulated in the Sovereign Development Fund, and greater confidence in obtaining financial support from international financial institutions and neighbouring countries.
The Ministry said Moody’s had acknowledged the effectiveness of the Government’s policies in achieving these improvements.
Measures on foreign exchange introduced since 2024 have also contributed to increased foreign currency inflows into the Maldivian banking system, resulting in higher official reserves and funds held in the Sovereign Development Fund, according to the Ministry.
The Ministry said these measures, together with lower expenditure required for external debt servicing, are expected to further strengthen the country’s fiscal position.
The Government has also strengthened its financial resilience through support from international financial institutions. According to the Ministry, the Government has secured a total of USD 130 million in assistance, including USD 40 million from the World Bank, USD 50 million from the Asian Development Bank and USD 40 million from the OPEC Fund.
Ministry of Finance figures show that government debt, which stood at 129.2 per cent of GDP at the end of 2025, had declined to 122.6 per cent of GDP by the end of July 2026.
The Ministry attributed the decline to efforts to repay debt and the implementation of prudent fiscal policies.
The Government is also maintaining a strong focus on protecting essential services for the public, supporting economic activity and keeping government expenditure within the approved budget, while remaining mindful of challenges arising from global economic uncertainties and fluctuations in energy prices, the Ministry said.